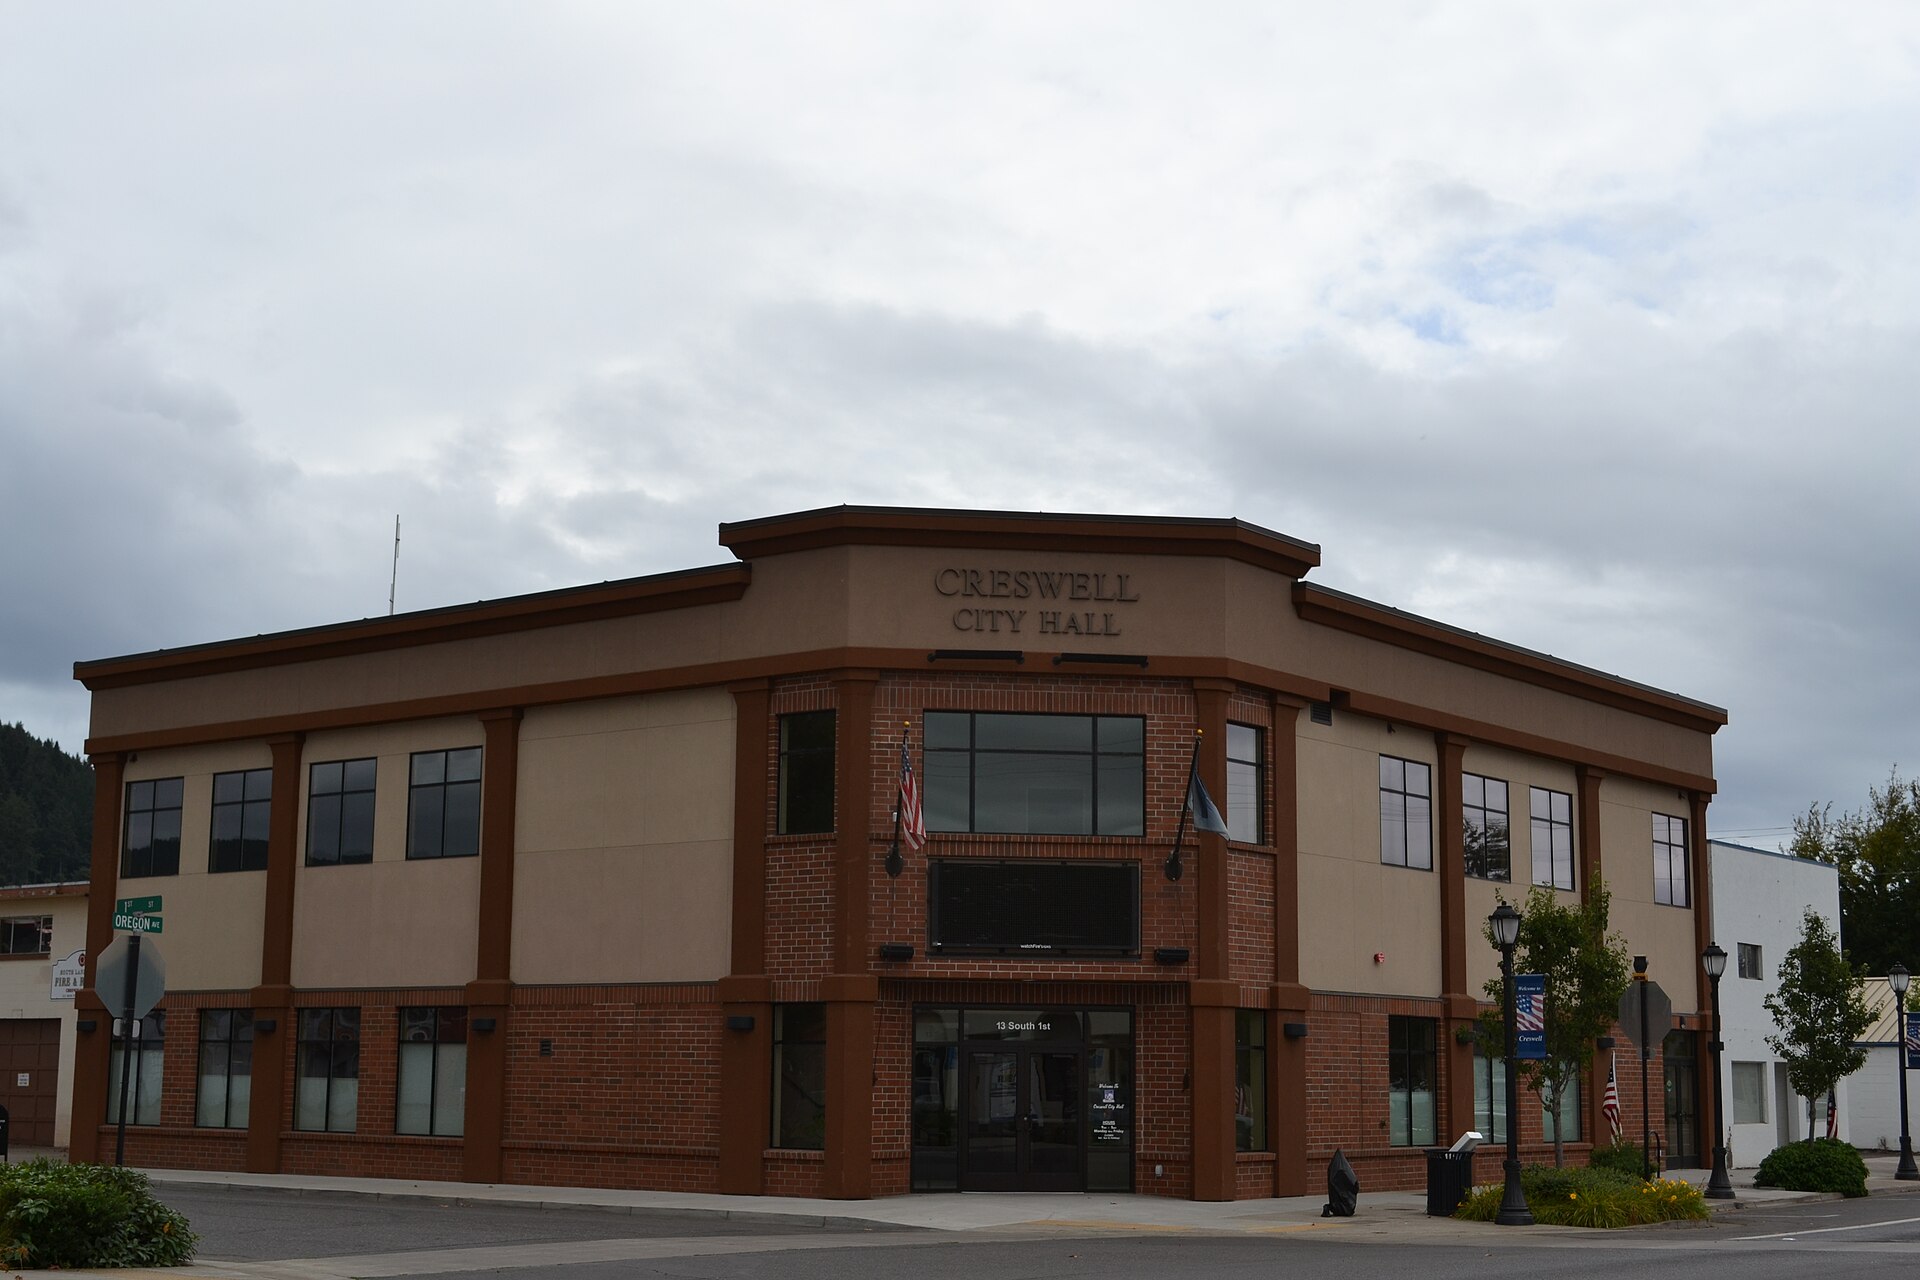
A mix of in-town homes on city services, newer subdivisions, and rural acreage in the surrounding farm country. Parts of the area have historically fallen within USDA eligible boundaries, which matters for buyers needing low down payment options. Check by address.
Layer the specialty on top of that. Oregon has real programs for first-time buyers. Below market rate loans through the state bond program, down payment assistance at the state and local level, and homebuyer education classes that unlock the rest. Most renters never find out because nobody ever walked them through it.
Generic advice is worthless on a decision this size. This is what first-time buyers actually involves in Creswell, as opposed to anywhere else in the county.
Parts of the county outside the Eugene and Springfield core have historically fallen inside USDA Rural Development boundaries, which can mean a loan with no down payment for buyers who qualify. Eligibility is decided address by address and the maps get updated, so the only reliable move is to check the specific property rather than assume based on the town name. If it applies to you, it is one of the most useful programs available.
In Creswell you are buying into services, walkability, and a shorter drive, and paying for them in price per square foot. For a first purchase that trade is often the right one, because a smaller place in a location you love beats a larger one you resent driving to.
Creswell School District serves Creswell. School assignment in Lane County is by address rather than by the boundary people assume, and district lines do not always follow the obvious streets. If schools matter to your decision, verify the assignment for the specific property with the district rather than trusting a listing field.
Two calls. A lender approved for Oregon Flex Lending, to find out what you qualify for and what the payment really looks like with taxes and insurance. And DevNW in Springfield, which is the designated homeownership center for Lane County, to ask what down payment assistance is currently funded and when the next homebuyer education class runs. Programs change and city-level funds go in and out, so ask rather than read.
Creswell sits on the useful edge: a real town with its own identity and services, close enough to the metro that the drive is a commute rather than an expedition. That combination is why it holds value. You are trading a little convenience for a lot of character and usually a better price per square foot.
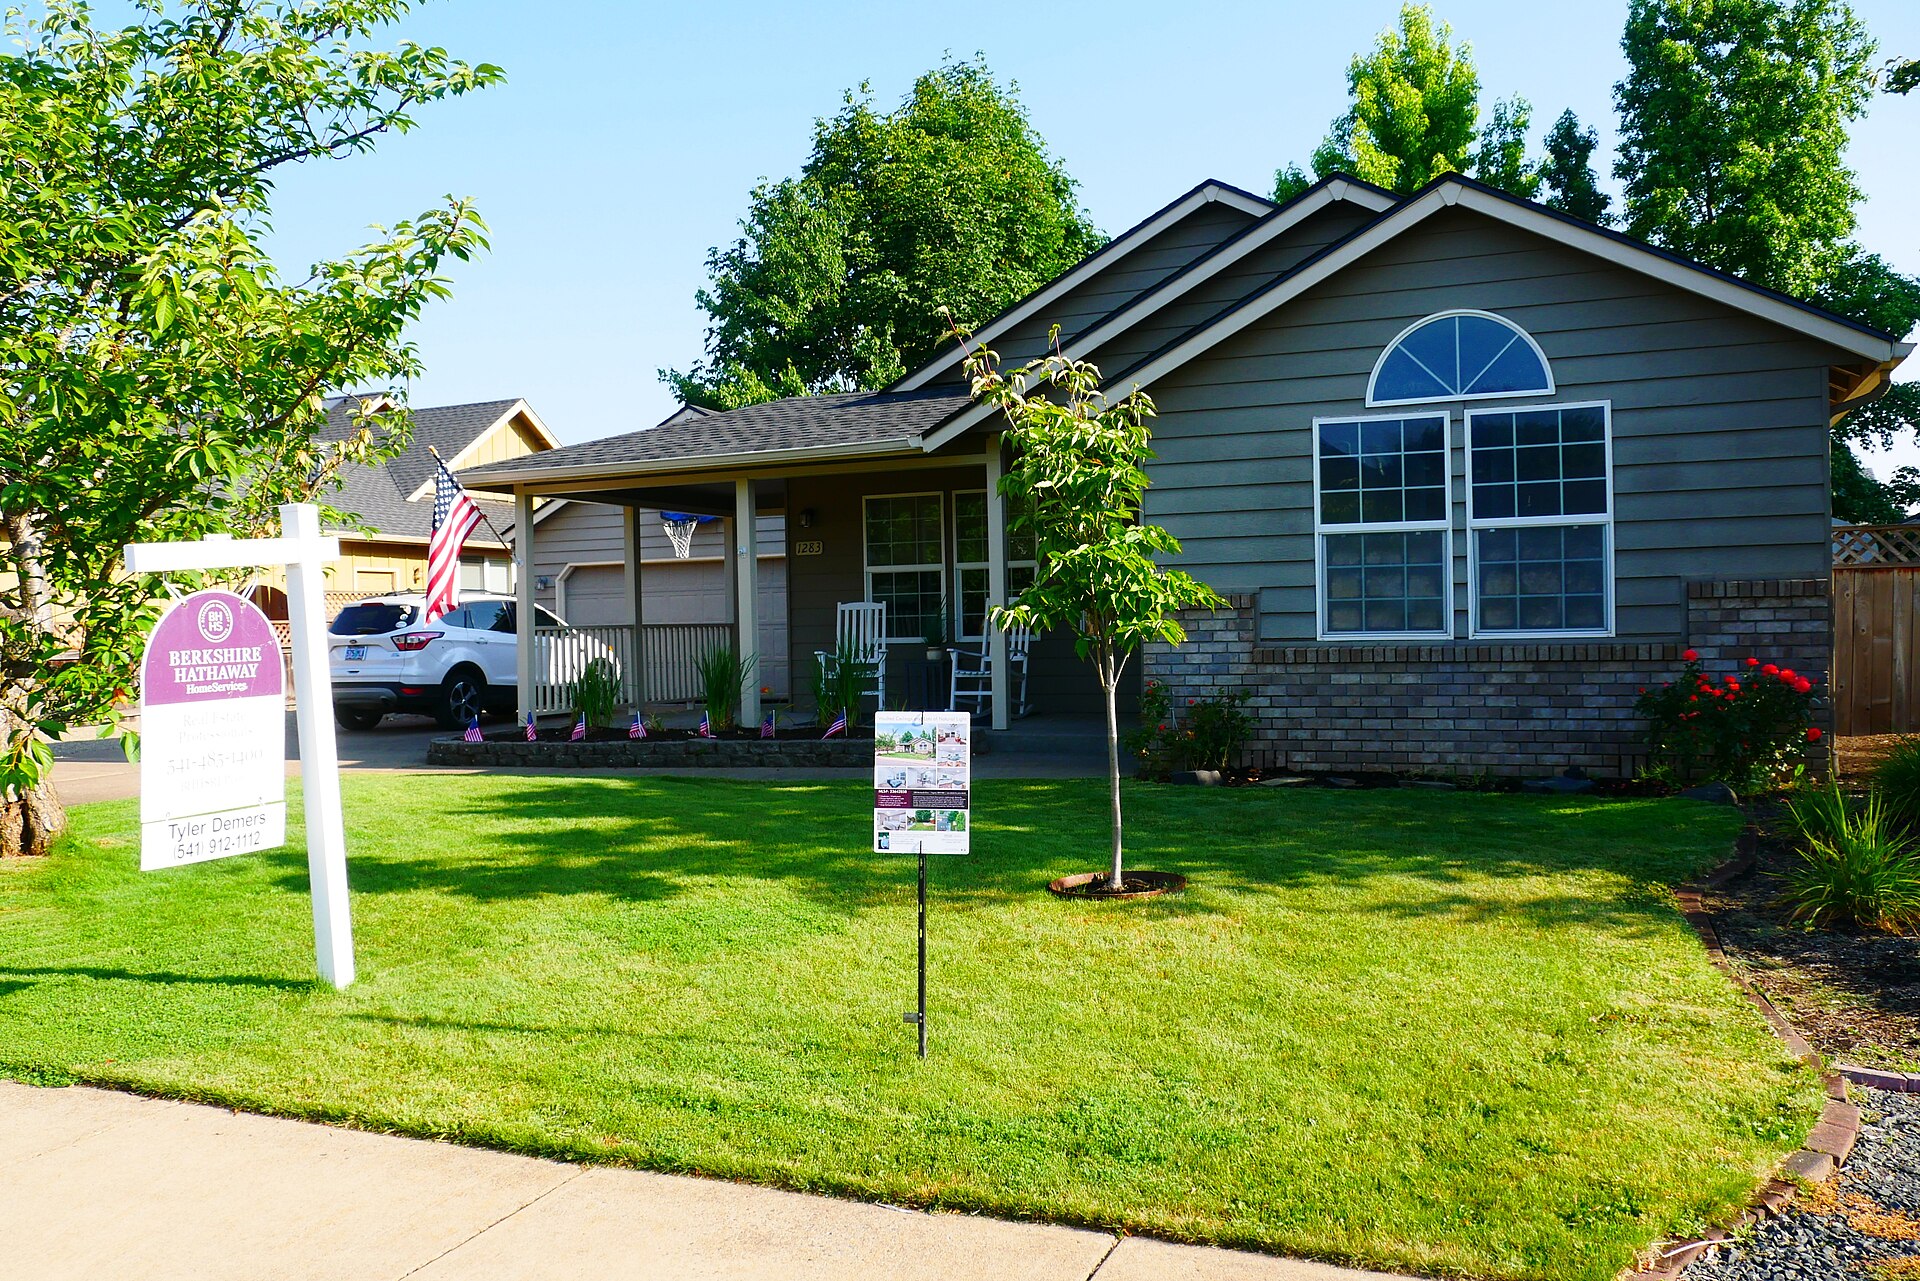
Creswell is a small city on I-5 just south of the metro that has grown steadily because the math works: you get a real downtown, a school district of its own, and a genuinely short commute. It has an airport, a main street, and enough farm ground around it to feel like a town rather than a suburb.
| ZIP codes | 97426 |
| Known for | Creswell Airport (Hobby Field) · Downtown Creswell · Camas Swale · Interstate 5 access |
| Schools | Creswell School District serves the community. |
| Getting to town | A straight interstate run to Eugene |

You want someone who combines real first-time buyers experience with parcel-level knowledge of Creswell. Brett Herring works Creswell as part of his core Lane County territory with The Operative Group at Real Broker, LLC, and lives in Springfield. Call or text 541-968-9422 for a straight local conversation with no pressure attached.
A mix of in-town homes on city services, newer subdivisions, and rural acreage in the surrounding farm country. Parts of the area have historically fallen within USDA eligible boundaries, which matters for buyers needing low down payment options. Check by address.
No. This is the most common and most expensive misconception in the whole process. Many loan programs allow far less, and Oregon down payment assistance can help with what remains. Ask a lender what you actually qualify for before you write off buying.
There are loan paths at a range of credit levels, and the cutoff people imagine is usually higher than reality. If your credit needs work, a good lender will tell you exactly which two or three things to fix and roughly how long it takes. That is a plan, not a rejection.
Closing costs cover lender fees, title, escrow, prepaid taxes and insurance, and recording. They typically run a few percent of the purchase price. Some can be negotiated into the deal, some can be covered by assistance programs, and all of them should be shown to you in writing well before closing.
Buying your first place, selling acreage out east, or landing here from out of state — start with a conversation. No pressure, no script, no disappearing act.
541-968-9422I read these myself. Expect a reply from me, usually the same day.